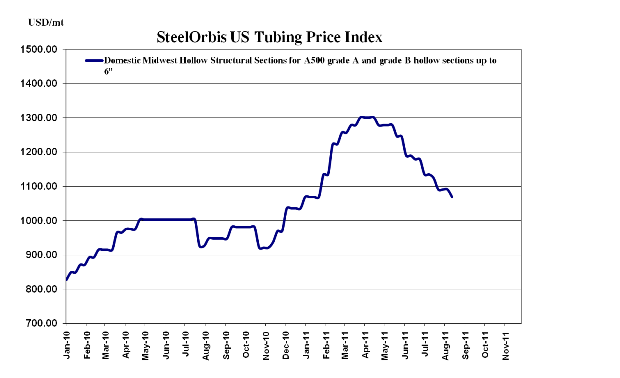
US domestic hollow structural sections (HSS) spot prices are still falling as buyers struggle to keep resale prices up.
Still constrained by weak demand and buyers' reluctance to fill inventory holes, HSS spot prices have registered yet another decline. After falling about $1.50 cwt. ($33/mt or $30/nt) two weeks ago, spot prices have fallen $1.00 cwt. since early August to $48.00-$49.00 cwt. ($1,058-$1,080/mt or $960-$980/nt) ex-Midwest mill. Additionally, while most US domestic flat-rolled mills attempted to stem falling spot prices last week with a $3.00 cwt. ($66/mt or $60/nt) spot price increase, sources tell SteelOrbis that domestic tubing mills are paying little attention to the move at the moment, and are not expected to announce any price increases of their own unless flats prices begin to firm, and stay that way. Domestic tubing mills aren't likely to raise prices immediately particularly because the market is still uncertain and buyers are unlikely to accept higher prices under current demand conditions.
What's more, deals below the above spot price range are not uncommon. One Southeast distributor source explained that domestic mill order books are so weak that mills are consistently asking customers, "What price do you need to place an order today?" With US domestic HSS spot prices moving lower on an almost week-on-week basis, mimicking the price slide of US domestic flat-rolled prices, service center sources tell SteelOrbis that existing inventories have been devalued substantially, and it is not uncommon for some to sell HSS below replacement cost in some cases in order to keep market share. Additionally, with end-use demand largely at a standstill, HSS spot prices are expected to keep falling throughout August, with another $1.00-$2.00 cwt. ($22-$44/mt or $20-$40/nt) drop all but guaranteed.
As long as US domestic HSS spot prices are still slipping backward, US buyers will continue to shy away from booking anything from offshore. Turkish offers have been quiet in the last month due to a weak domestic Turkish tubing market in July, but even new prices in the range of $44.50-$45.50 ($981-$1,003/mt or $890-$910/nt) DDP loaded truck in US Gulf ports, down about $2.50 cwt. ($55/mt or $50/nt) in the last month and $3.50 cwt. ($77/mt or $70/nt) lower than US spot prices, are too high for US buyers to consider.