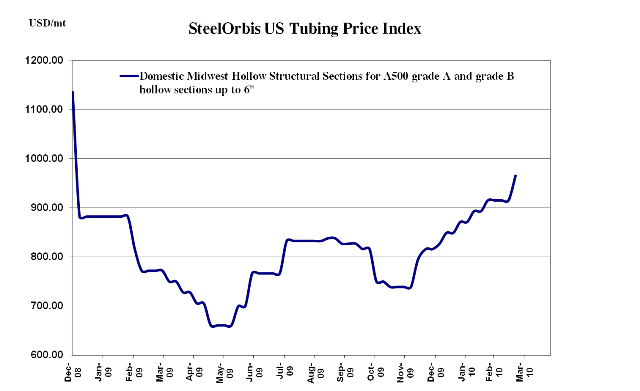
Spot prices for Midwest US hollow structural section (HSS) tubing have ticked up further since our last report two weeks ago, despite market conditions remaining rather stagnant.
Most domestic spot offers have increased approximately $2.00 cwt. ($44/mt or $40/nt) over the past two weeks and are now being seen at approximately $43.50 cwt. to $44.00 cwt. ($959/mt to$970/mt or $870/nt to $880/nt) ex- Midwest mill, although, as a result of the latest $2.50 cwt. ($55/mt or $50/nt) mill increase announced a couple weeks ago, most domestic mills are now pushing for offers within a range of $45.00 cwt. $46.00 cwt. ($992/mt to $1,014/mt or $900/nt to $920/nt) ex-Midwest mills. Mills are likely to eventually get that full asking price but spot price momentum is tied almost solely to surges in raw materials and is not reflective of tubing buying activity.
However, as long as the cost of raw materials continues to rise, the trickle-down effect to tubing will remain in place. Most spot offers will continue to trend slightly up over at least the next few weeks, unless something drastic occurs in the raw materials markets; however, the lag in demand and product necessity will continue to create a modest gap of about $1.00 cwt. ($22/mt or $20/nt) between spot and mill offer prices. And while commercial construction is starting to trend modestly up, and buyers hope that the spring thaw may release some bigger jobs, current and projected activity is not expected to provide much relief for distributors.
Switching to offshore offers, traders continue to find it difficult to justify purchasing from foreign sources with uncertain US domestic market prices and conditions. Imported lead times would bring product to the states in the middle of summer, which is just too far off for most to speculate about at this point. While offers from Korea have fallen off the map since earlier this month, there has been some renewed interest in Turkish HSS offers, which, after a recent $2.00 cwt. ($44/mt or $40/nt) increase, may now be booked at around $39.50 cwt. to $40.50 cwt. ($871/mt to $893/mt or $970/nt to $910/nt) duty-paid, FOB loaded truck in US Gulf ports.