Global steel excess capacity is projected to increase from 601 million mt in 2024 to 721 million mt by 2027, undermining producers' ability to invest in low-emission technologies and raising the risk that subsidized capacity expansion will further delay the industry's decarbonization, according to the OECD's report, Navigating the Steel Transition amid Global Excess Capacity.
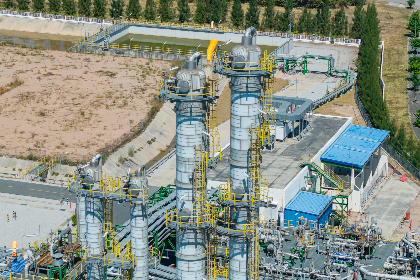
The organization stated that persistent overcapacity depresses steel prices, squeezes profit margins and increases financing costs, while government support that sustains inefficient producers slows the retirement of emission-intensive facilities.
BF-BOF capacity additions continue to outpace closures
According to the report, approximately 25.8 million mt of blast furnace-basic oxygen furnace (BF-BOF) capacity is expected to be withdrawn during 2025-2027, including 15.6 million mt in China, accounting for around 60 percent of the total. However, these closures will be outweighed by 62.1 million mt of new BF-BOF capacity, primarily in China and India. Only 6.9 million mt, or 27 percent, of the identified BOF closures are associated with corresponding electric arc furnace (EAF) installations at the same locations, suggesting that deteriorating market conditions remain a stronger driver of closures than decarbonization.
Meanwhile, Chinese overseas investment is contributing to the relocation of emission-intensive production, with around 60 million mt of anticipated capacity expansion in ASEAN linked to Chinese investment, potentially prolonging reliance on high-emission steelmaking.
DRI and EAF expansion does not necessarily reflect decarbonization
The OECD identified 30.7 million mt of planned direct reduced iron-electric arc furnace (DRI-EAF) steelmaking capacity additions and 61.7 million mt of scrap-based EAF additions during 2025-2027. Nevertheless, much of this expansion reflects raw material availability, energy advantages and expectations of stronger demand rather than explicit emissions reduction strategies.
Among the DRI projects scheduled to come online by 2027, only around 19 million mt of capacity appears to be driven by low-emission objectives. The report emphasized that DRI production is not inherently low-emission, particularly where coal-based technologies are used, while natural gas-based projects require credible plans for a subsequent transition to hydrogen to support near-zero-emission production.
Low-emission projects face delays as investment conditions weaken
As of the second quarter of 2025, announced low-emission steelmaking projects representing 15.5 million mt of capacity had been suspended or postponed amid excess capacity, high energy costs and regulatory uncertainty. Projects involving conversion from BF-BOF to EAF production recorded the highest suspension rate at 27 percent, followed by hydrogen-based DRI projects at 18 percent and carbon capture, utilization and storage projects at 15 percent.
The OECD noted that weaker profitability restricts internal funding while earnings volatility and higher borrowing costs make external financing more difficult, leaving producers with limited financial capacity for major technological upgrades.
Lower conventional steel prices increase the relative green premium
Falling conventional steel prices also weaken the commercial case for low-emission products by increasing the relative premium buyers would need to pay. Using an estimated production cost difference of approximately $160/mt between conventional BF-BOF steel and green hydrogen-based DRI-EAF steel in Europe, the OECD calculated that declining hot rolled coil prices during 2022-2025 increased the implied relative premium from 17 percent to 25 percent.
Similar calculations showed increases from 16 percent to 22 percent in China and from 15 percent to 22 percent in Japan, illustrating how depressed conventional steel prices can discourage demand for cleaner alternatives even when the absolute production cost gap remains unchanged.
Transition policies must support capacity retirement
The OECD warned that subsidized expansion of lower-emission steelmaking could generate a new wave of excess capacity unless investment incentives are accompanied by effective retirement of existing facilities.
In economies driving oversupply, the organization called for transition measures to be combined with mandatory closures, binding capacity replacement requirements and the removal of market-distorting subsidies. Meanwhile, carbon-related market access requirements can help protect investment in cleaner production, although subsidized low-emission imports could still undermine market-based producers.
The report concluded that addressing excess capacity is essential to restoring investment capacity and strengthening demand for low-emission steel, while decarbonization policies should promote genuine restructuring rather than simply change the technological composition of global oversupply.