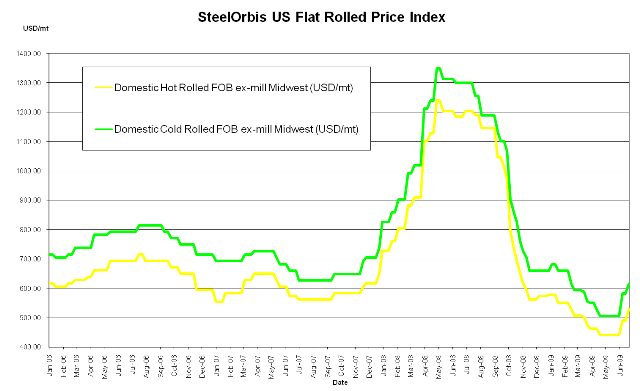
US flats mills are attempting to increase their prices by about another $2.00 cwt. ($44 /mt or $40 /nt) for September shipments; however, buyers' skepticism of the rising prices suggests that the recent series of price hikes may not be sustained the rest of the year.
Since US HRC and CRC prices finally crept over the $20.00 cwt. ($441 /mt or $440 /nt) and $24.00 cwt. ($529 /mt or $480 /nt) thresholds (ex-mill in the Midwest) , respectively, at the end of May, market prices have been increasing on an almost weekly basis following successive spot price increases from the US mills.
US domestic HRC spot prices increased by about another $1.50 cwt. ($11 /mt or $10 /nt) over the past week, and now range from approximately $23.00 cwt. to $25.00 cwt. ($507 /mt to $551 /mt or $460 /nt to $500 /nt) ex-mill in the Midwest. While spot prices have not quite reached the desired mill level, AK Steel officially announced to customers Thursday that it will increase HRC prices for August and September shipments by an additional $2.00 cwt. ($44 /mt or $40 /nt), which is the same amount other integrated mills are reportedly asking for in September. With this latest round of increases, mills are aiming to firm spot prices for HRC up to at least the $25.00 cwt. ($551 /mt or $500 /nt) level. However, most mills have not yet filled their August order books, so it remains to be seen whether there will be enough demand for mills to easily book September at the new price levels. Several mills, including market-leading minimill Nucor, have yet to open their September books.
US CRC spot prices have also increased by an additional $1.00 cwt. ($22 /mt or $20 /nt) since last week. While some spot deals may still be found on the low end at around $27.00 cwt. ($573 /mt or $520 /nt), other spot offers are as high as $29.00 cwt. ($639 /mt or $580 /nt), both ex-mill in the Midwest. Furthermore, AK Steel announced Thursday to customers that it will be raising CRC prices for August and September shipments by $2.50 ($55 /mt or $50 /nt). With this third round of price increases since June, AK and its fellow integrated mills are aiming to push CRC offers back up to the $30.00 cwt. ($661 /mt or $600 /nt) level.
However, while US flats' upward price momentum continues r, the sentiment portrayed by domestic mills that "buyers are scrambling" for orders may be a bit disingenuous. Several buyers have informed SteelOrbis that any inventory gaps they had are close to being filled, if not filled already, and the need for more product just isn't there. While inventory re-stocking activity has allowed domestic flats mills to raise spot prices in recent weeks, the lack of strong demand may prevent flats prices from increasing much further past September/October.
On the import side, traders have informed SteelOrbis that offers for HRC are virtually dead right now, while CRC offers aren't at all competitive. Foreign sources appear content to wait for US prices to continue increasing before actively entering the market again. Furthermore, lead times are said to be all over the map again. While import offers could pick up again in the coming weeks and months if US prices continue to climb, any bookings are unlikely to deliver product to the US until the fourth quarter. Of the few offers out there, China is offering CRC for around $32.00 cwt to $34.00 cwt. ($705 /mt to $750 /mt or $640 /nt to $680 /nt) duty-paid, FOB loaded truck in US Gulf ports. SteelOrbis has heard that Chinese mills could still offer some CRC to the US for August shipments, but they are not aggressively looking for orders.