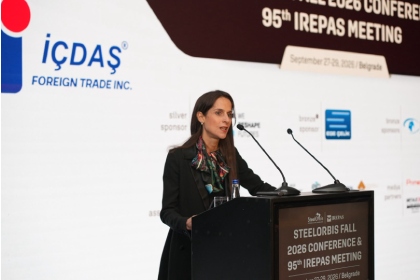
Geopolitical disruptions are increasingly affecting steel trade flows, voyage lengths and freight costs, according to Maria Bertzeletou, senior market analyst at The Signal Group, speaking at the SteelOrbis Fall 2026 Conference & 95th IREPAS Meeting in Belgrade on September 28.
Ms. Bertzeletou stated that dry bulk freight earnings have increased significantly. During September 1-23, average Capesize earnings reached $50,300/day, up 96 percent year on year, while Panamax, Supramax and Handysize earnings averaged $21,300/day, $19,700/day and $16,900/day, respectively. She stressed that, for individual steel shipments, freight costs also depend heavily on whether a suitable vessel is available in the required region.
Black Sea risks add to freight and insurance costs
In the Black Sea, the expansion of the London-based Joint War Committee's listed war-risk zone has added to shipping risks and insurance costs. Bertzeletou cited estimates indicating that war-risk insurance could reach three to five percent of a vessel's value. Higher freight quotations have been reported for Black Sea billet shipments to Turkey, although she noted that she had not seen completed fixtures confirmed at those levels.
Meanwhile, scrap cargoes are competing with steel for available tonnage. Scrap demand has supported Mediterranean voyages, and cargo demand combined with limited vessel availability has strengthened Handysize rates in the US Gulf. Bertzeletou also cited indications of strong rates for scrap shipments into the eastern Mediterranean, while stressing that these were market indications rather than confirmed fixtures.
China accounts for 41.6 percent of recorded seaborne steel volumes
Turning to steel trade, China accounted for 41.6 percent of seaborne steel volumes recorded by The Signal Group, followed by Japan with 10.8 percent and South Korea with 9.2 percent. Destinations were considerably more fragmented.
Overall global seaborne steel loadings declined by 3.3 percent year on year in January-August 2026, while August volumes increased to approximately 23.2 million mt from 21 million mt in August 2025.
Black Sea steel-related shipments fall sharply
The effects of geopolitical disruptions were particularly visible in the Black Sea. For the selected Russian Black Sea and Azov Sea ports and steel-related cargoes, July-August loadings fell by approximately 79 percent year on year, while recorded voyages decreased to 21 from 135. No voyages for the selected ports and cargoes were recorded during September 1-22.
Russian Baltic steel-related loadings also weakened, averaging 0.62 million mt per month in July-August, compared with 0.73 million mt in January-June. Russian steel and related cargoes discharged in the eastern Mediterranean fell by 39 percent year on year to 3.64 million mt in January-August. Ukrainian seaborne trade has also fallen sharply. For the selected steel and mineral cargoes, January-August loadings declined from 7.7 million mt in 2021 to just 0.5 million mt in 2026.
Steel intake through Strait of Hormuz declines 65 percent
Disruptions were also evident around the Strait of Hormuz. A selected AIS waypoint indicator remained significantly below its 2023-25 seasonal average after February 2026. Nevertheless, a separate transit log recorded 98 passage events by bulk carriers and multipurpose vessels during September 1-23, demonstrating that vessels continued to transit the strait.
Selected steel intake through the Strait of Hormuz totaled approximately 3.8 million mt in January-August 2026, down around 65 percent from 10.95 million mt in the corresponding period of 2025.
Higher bunker prices add pressure to freight quotations
Higher fuel costs have added further pressure to freight. The global 20-port average price for very low sulphur fuel oil increased by approximately 62 percent, from $543.5/mt on February 27 to $881/mt on September 24.
Bertzeletou stated that higher bunker prices increase voyage costs and put upward pressure on freight quotations, although the impact varies according to fuel grade, port and contractual terms. She concluded that freight levels for individual steel shipments ultimately depend on the specific cargo, route and vessel availability at the time of fixing. According to Bertzeletou, geopolitical risks are expected to play an increasingly important role in determining freight costs alongside the underlying balance between vessel supply and cargo demand.