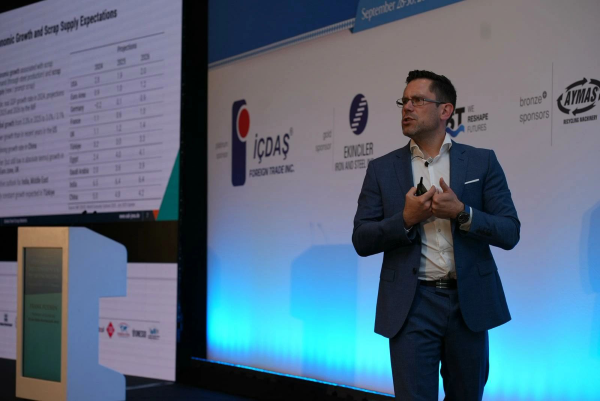
During his presentation at the SteelOrbis 2025 Fall Conference & 93rd IREPAS Meeting held in Munich on September 28-30, Frank Pothen, professor at Ernst-Abbe-Hochschule Jena, pointed out the profound changes and uncertainties shaping the global steel scrap markets. After decades of expansion, the industry is entering a new phase of stagnating crude steel output, shifting regional balances, and persistent policy risks.
Global crude steel production has stabilized at around 1.9 billion mt since 2019, slipping from 1.904 billion mt in 2023 to 1.885 billion mt in 2024, with China still accounting for more than half of the total at 1.005 billion mt. Behind these figures, however, lie sharp divergences: while India boosted output by 47 percent between 2017 and 2024, the EU, Japan, and South Korea saw steep declines, and production in the US and Turkey stagnated.
Scrap consumption in key recycling regions (China, EU, US, Japan, Turkey, India, South Korea) edged down from 459 milion mt in 2023 to 457 million mt in 2024. India (+21.5%), Turkey (+7.5%) and the EU (+1.9%) registered growth, most other regions recorded declines. Despite these shifts, global trade volumes held steady at around 90 million mt annually, though prices have remained weak since 2022 due to sluggish demand in mature markets.
On the macroeconomic outlook, Professor Pothen noted that global GDP growth is expected to slow from 3.3 percent in 2025 to around 3.0-3.1 percent in 2026, with weak performances in the US and China contrasting with stronger momentum in India, the Middle East and Turkey. The construction sector, a major source of scrap, remains under pressure, particularly in China where activity is set to fall by more than 10 percent in 2025. A recovery is forecast for 2026, led by infrastructure, with positive spillovers in Europe and the Middle East.
Looking further ahead, post-consumer scrap availability in Europe will grow only slowly (+1.6% annually until 2050), shifting toward lower-grade material. China, by contrast, is expected to see accelerating scrap generation as its steel stock matures. OECD forecasts suggest global crude steel output could climb back toward 2 billion mt by 2030, with declines in China, Japan and South Korea offset by strong growth in India, the Middle East and the ASEAN region. This will increasingly concentrate scrap demand in South and Southeast Asia and the Middle East, while the global expansion of electric arc furnace (EAF) capacity will boost demand but also heighten competition with DRI/HBI.
On trade policy, Pothen warned that protectionist measures remain a key risk. Export bans and restrictions have historically cut trade flows by up to 80-95 percent, and ongoing debates in the EU, UK and US highlight the fragility of current arrangements. “Scrap always finds its way into markets,” he said, noting that, while partial restrictions redirect flows, strict and comprehensive barriers could trigger sharp price and volume effects.
Pothen concluded that the coming years will be shaped by the geographic shift of scrap demand toward India, the Middle East and the ASEAN region, the recovery of construction, the rise of EAF-based steelmaking, and the growing need for high-quality scrap. Yet unresolved policy debates and uneven growth mean uncertainty will remain a defining feature of the global scrap market, he noted.